Insurance Claims Assistance in Daly City, CA
Answered live 24/7 Free inspection Direct insurance billing
Get a Free Estimate
Use the form or call our 24-hour hotline at (201) 277-9344.
- 24/7 Emergency Service
- Free On-Site Inspection
- Direct Insurance Billing
- Local Daly City Crews
Trusted Insurance Claims Assistance in Daly City
Insurance claims assistance means we document your water loss the way carriers expect and bill them directly, and Water Damage Daly City does it from the first hour. The water is bad enough. Then comes the second problem: the claim. You are standing in a wet hallway trying to work out what your policy covers, what your adjuster needs, and whether one wrong word on the phone is going to sink the whole thing. For most homeowners a water loss is the first big claim they have ever filed, and the paperwork can feel designed to be confusing.
Here is where claims go wrong. The damage gets cleaned up before it is documented, so there is no proof of how bad it was. The scope is vague, the moisture readings are missing, and the water category and damage class that carriers rely on were never recorded. By the time the adjuster starts asking questions, the evidence has been dried out, hauled to the curb, and painted over, and now you are arguing from memory against a file that has none.
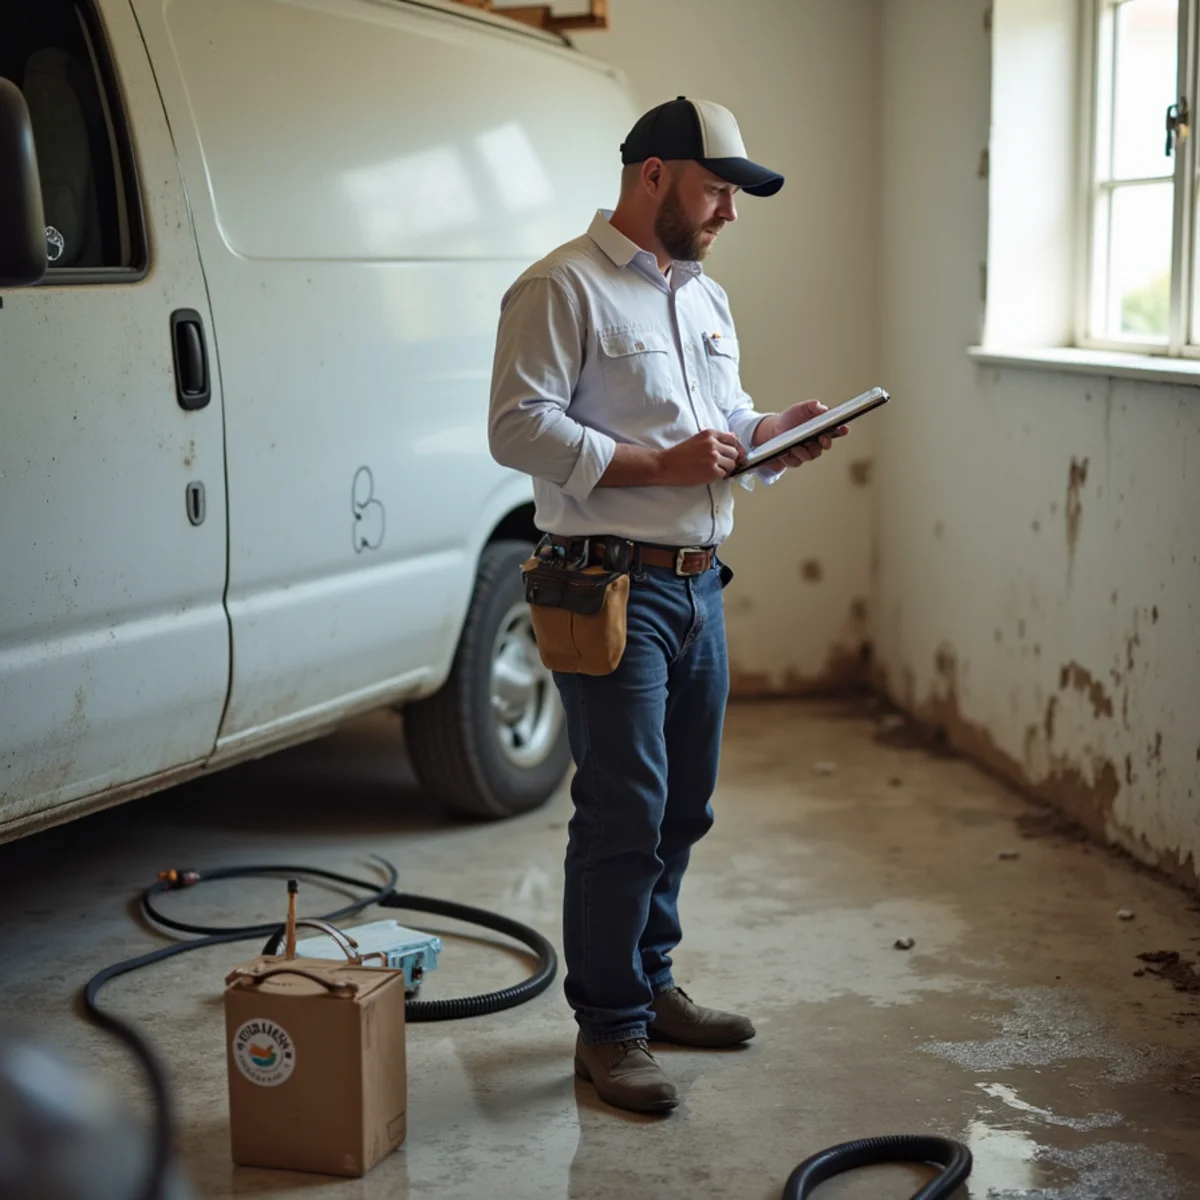
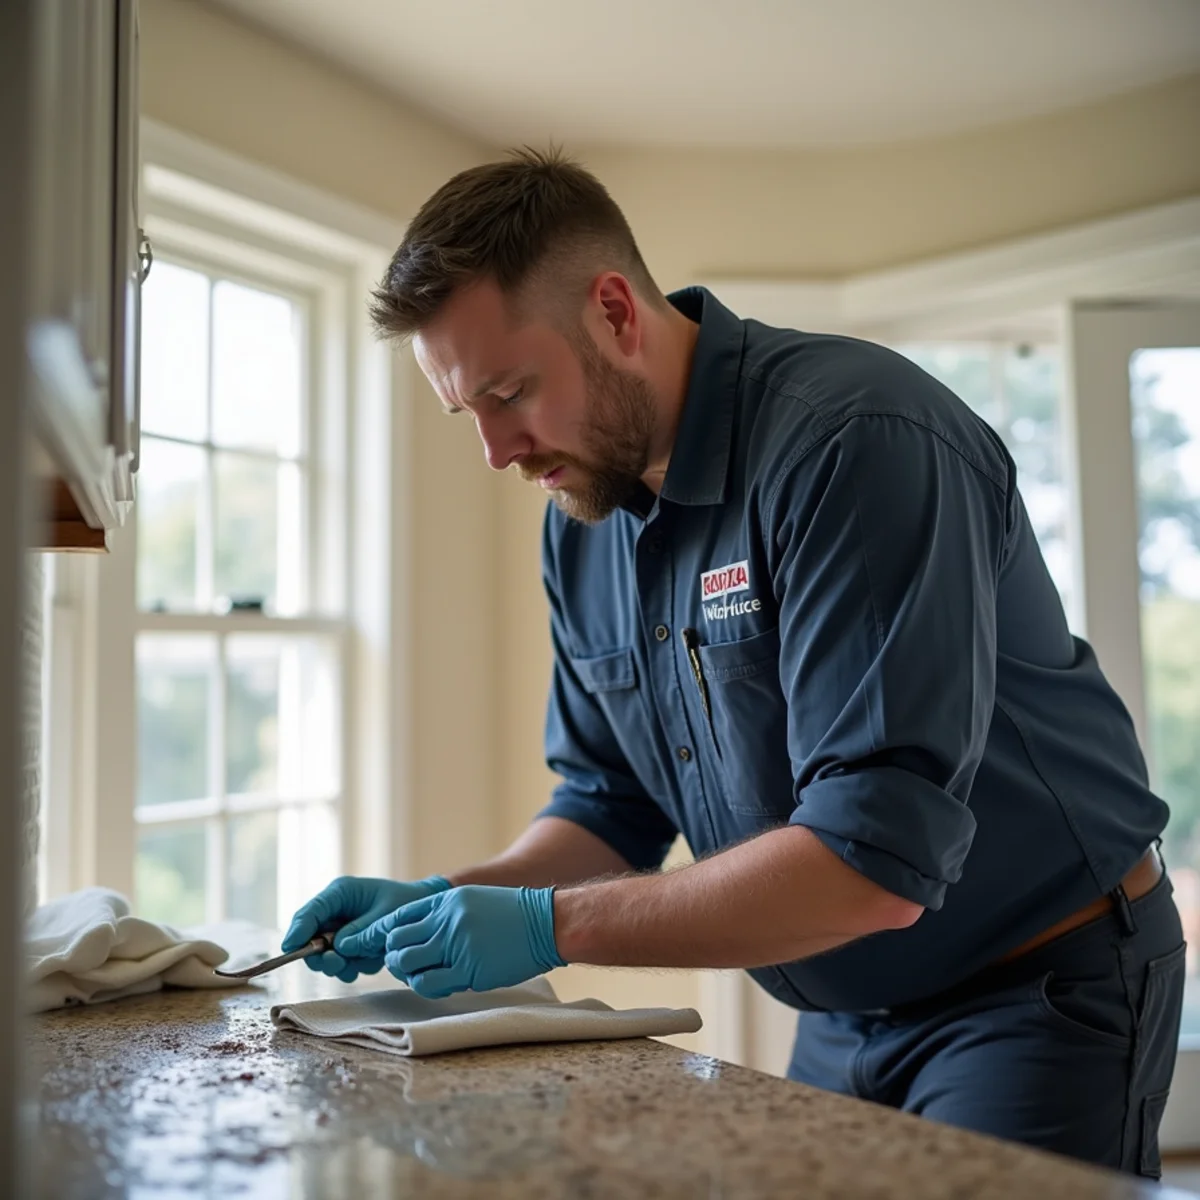
We build that file correctly from the start. We photograph and measure everything, record readings to the IICRC S500 standard, classify the loss, and speak the adjuster's language so your claim rests on evidence instead of recollection. This is claims support and education, not legal or public-adjusting advice, and your policy and your carrier always have the final say on coverage. To get your loss documented properly, call (201) 277-9344 before the evidence disappears.
What’s included
- Thorough photo and moisture documentation from the very first visit
- Loss recorded by IICRC water category and damage class
- Detailed, itemized scope of the work in the format carriers expect
- Direct billing to all major insurance carriers
- Coordination and clear communication with your adjuster
- Records of removed materials and packed-out contents for your claim file
- Plain-language explanations of the process at every step
When to call for insurance claims
Catching these early keeps a small problem from becoming a major one.
You are not sure what your policy covers
Sudden-and-accidental losses like a burst supply line are usually covered, while slow, long-term leaks and true flooding are often treated differently or excluded. We help you understand that distinction so you know what to expect, and we encourage you to confirm the specifics with your own carrier, who has the final word.
The damage is being cleaned up before it is recorded
Documentation has to come before demolition, every time. If wet drywall and soaked flooring are torn out without photos, moisture readings, and measurements, the proof of your loss leaves with the debris. We capture the evidence first, then open the walls.
The adjuster's scope feels thin
When an initial estimate misses hidden moisture in the framing, affected subfloor, or packed-away contents, the claim can fall short of what the repair actually costs. A detailed, standard-based scope from the crew that measured the loss gives the adjuster a fuller, harder-to-dispute picture.
It is a condo or HOA loss with split responsibility
In a Serramonte townhome or a shared-wall condo, the line between the association's policy and your own is rarely obvious, and an upstairs-unit leak can cross it. We document the loss clearly so the right parties and the right policies are looking at the same evidence.
You do not want to float the cost
Paying out of pocket and chasing reimbursement is a heavy weight during an already hard week. Direct billing to the carrier keeps you from fronting the full cost of the restoration while you wait for a check that takes its time arriving.
What to do before our crew arrives
Safe, simple steps that limit the damage while help is on the way.
- 1
Stop the water and take reasonable steps to prevent more damage. Most policies expect it, and waiting can hurt the claim.
- 2
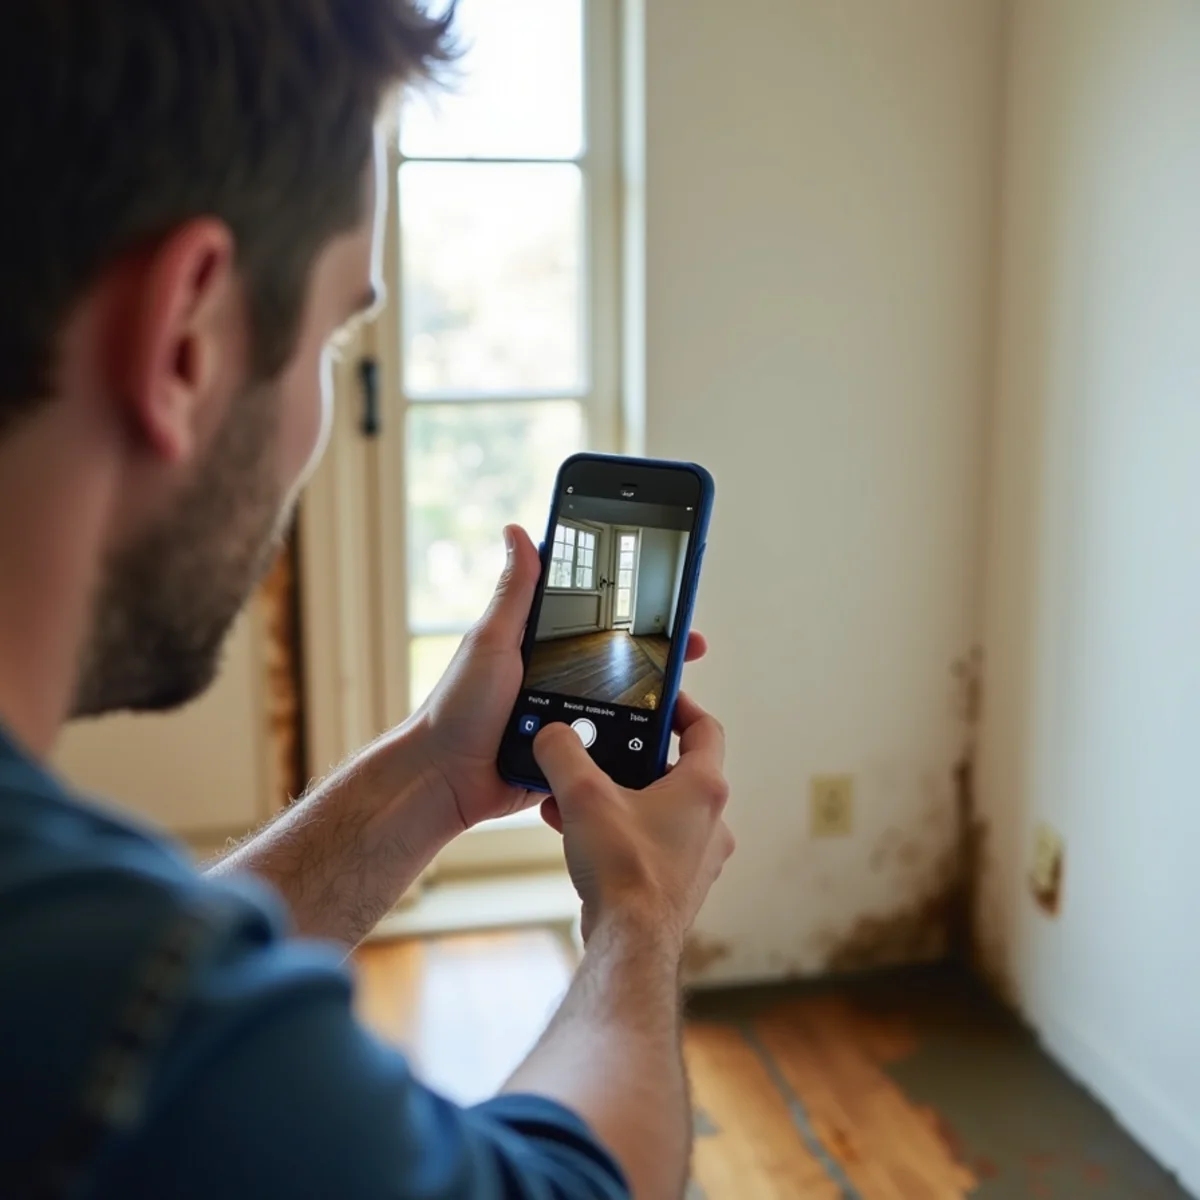
Video and photograph every affected room before anything moves, and keep the failed part (a burst hose, cracked fitting, or split supply line) instead of letting it be thrown out.
- 3
Find your policy number and declarations page, open the claim by phone or app, and write down the claim number and your adjuster's name.
- 4
Keep every receipt for emergency purchases, hotel stays, and meals while you are displaced. Additional living expense coverage, if you have it, depends on them.
- 5
Keep a simple call log with the date, the person you spoke with, and what was said.
- 6
Read any document before you sign it, especially anything that assigns your insurance benefits, and ask questions if the terms are unclear.
How we handle insurance claims
- 1
Document before we touch anything
On the first visit we photograph the damage, take moisture readings, measure the affected areas, and classify the loss by water category and damage class. That record is the foundation the entire claim stands on, and it can only be captured before cleanup begins.
- 2
Build a detailed scope
We prepare an itemized scope of the mitigation and repairs in the format carriers use, line by line. The adjuster reviews a clear account of what the loss requires and why, rather than a vague summary that invites questions and delays.
- 3
Coordinate with your adjuster
We share our documentation, walk the adjuster through what we found in the field, and answer the technical questions about drying, materials, and IICRC standards. Keeping the conversation grounded in evidence and readings keeps it moving instead of stalling on disagreement.
- 4
Track changes as work proceeds
If hidden damage turns up once the walls are opened, and in older homes it often does, we document it and update the scope. The claim then reflects what the loss actually required, not only what was visible on day one before anyone looked inside the wall.
- 5
Bill the carrier directly
We invoice your insurer for the covered work and provide the supporting records that back every line. You handle your deductible rather than the full cost of the restoration, and you are not stuck reconciling paperwork between us and your carrier.
How long insurance claims takes
Mitigation doesn't wait for the claim. Drying starts right away, while the carrier acknowledges the claim, assigns an adjuster, and schedules an inspection. Reconstruction usually waits until the repair scope is reviewed. Claims move faster when documentation is complete from the first visit and the cause is a clear, sudden event like a burst line. They slow down when the carrier questions whether a leak was gradual, when hidden damage requires a supplement after the walls are opened, or when an HOA master policy and a unit owner's policy split the loss. California has fair claims settlement rules that set response expectations for insurers, and the California Department of Insurance explains them and takes consumer complaints.
How to keep it from happening again
- Review your declarations page once a year and check whether you have a water backup or sewer backup endorsement, since many base policies exclude backups without one.
- Remember that flood from surface water is excluded from standard homeowners policies. Ask your agent whether separate flood coverage fits your location.
- Keep a folder of maintenance records such as water heater replacements, plumbing repairs, and roof work. They help answer "wear and tear" or "gradual leak" questions.
- Fix small drips promptly. Long-running leaks are the losses most likely to be limited or denied as gradual damage.
- Know your deductible and additional living expense limits before you need them. Our guide on whether homeowners insurance covers water damage in California explains the common gaps.
What goes into your estimate
Every water loss is different, so we never quote blind. After a free inspection we give you a clear, itemized estimate. These are the factors that move the price:
- The category and class of water, which shape the covered scope of work
- The extent of documentation and moisture mapping the loss requires
- Whether hidden damage is found once materials are opened up
- The mix of mitigation, contents handling, and reconstruction involved
- Your specific policy terms, coverage limits, and deductible
- Whether the cause is treated as sudden-and-accidental or gradual
- Coordination needs for condo or HOA losses with shared responsibility
Why Daly City trusts us for this
We build the file the way carriers read it
Photos, moisture logs, categories, classes, and an itemized scope are what actually move a claim forward. We produce that documentation as a matter of routine on every job, so your adjuster has what they need without a drawn-out back-and-forth that leaves you waiting.
Local experience with California water losses
Doelger-home pipe failures, slab leaks off John Daly Boulevard, and atmospheric-river storm damage are the losses Daly City and the Peninsula see most. We know how these specific losses tend to be scoped and what carriers look for in each.
Direct billing that keeps money out of your pocket
We bill all major carriers directly and supply the backup records to support it. You are not floating the cost of the job or chasing reimbursement paperwork while your house sits torn open and your family is displaced.
Straight talk, not sales pressure
We explain the process in plain language and stay in our lane. We handle restoration and documentation, and for coverage decisions that are not ours to make, we point you to your carrier or a licensed professional rather than pretending to be one.
Related Services
Helpful Reading
How to File a Water Damage Insurance Claim in California: Step-by-Step
Coverage is only half the question. Here is how a water damage claim actually moves, from the first call to your insurer to the final check, and the paperwork that keeps it moving.
Read article
Does Homeowners Insurance Cover Water Damage in California? (2026 Guide)
Sudden burst pipe? Usually covered. Slow leak or flood? Often not. Here’s how California water-damage coverage actually works.
Read article
Water Damage in Condos & HOAs: Who Is Responsible — Owner, HOA, or Neighbor?
A leak from the unit above raises one urgent question: whose problem is it? Here’s how condo and HOA responsibility really works.
Read articleInsurance Claims across Daly City & the Peninsula
We provide insurance claims throughout Daly City’s neighborhoods and the surrounding Peninsula — from the fog-belt hills to the coast to the bay. Not sure if we reach you? Call (201) 277-9344 and ask.
Insurance Claims questions, answered
Many sudden-and-accidental losses, like a burst pipe or a failed water heater, are commonly covered, while gradual leaks and flooding are often handled differently or excluded outright. Your policy is the final word, so we help you understand the categories and how the loss is likely to be classified, and we encourage you to confirm the specifics directly with your carrier.
You open the claim with your insurer, since it is your policy, and we support it from there. We provide the photo and moisture documentation, an itemized scope in the carrier's format, and direct communication with your adjuster, and we bill the carrier directly for the covered work so you are not the messenger between two parties.
Stop the water and stay safe, but do not throw damaged materials out before the loss is documented. We photograph and measure everything first, capturing readings and categories, so the proof of what happened is preserved. Once wet drywall is at the curb, it can no longer support your claim.
No. We are a local restoration company. We document the loss, scope the work to standard, and bill your insurer directly, and what we offer is education rather than legal or public-adjusting advice. For coverage disputes or questions about your rights, we point you to the appropriate licensed professional, because that work is theirs, not ours.
A denial is not always the end, and it often comes down to unclear documentation of what happened and when. Because we record the source, category of water, and moisture readings from our first visit, you have the evidence to support a reconsideration or a second look. We cannot practice law or negotiate as a public adjuster, but thorough restoration records give you much stronger footing.
We bill your insurance carrier directly for the covered portion of the work, so you are not fronting the full cost and waiting to be reimbursed. You are typically responsible only for your deductible. We go over exactly what your policy covers before we start, so there are no surprises on the final invoice.
24/7 Emergency Response
Need insurance claims in Daly City? Call now.
Call now for a free inspection. A real person answers day or night and dispatches a crew right away.